50% more leads on 30% less budget: The project workflow


How to achieve more with less budget
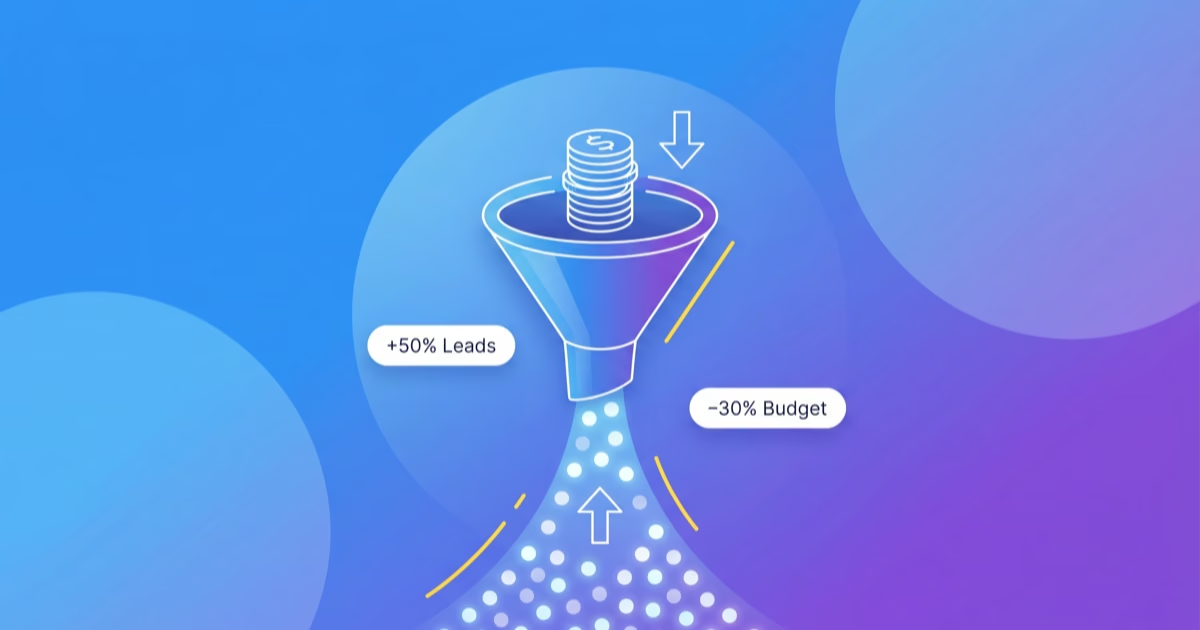
Before adding budget, this project reviewed the funnel, budget allocation and retargeting. The published account reports 50% more leads on 30% less budget. The limits of those figures are explained below.
The existing project account reports 50 percent more leads while the budget fell by almost a third. The workflow below describes the work; it does not isolate which change caused the result.
The starting problem
Click prices were rising, leads were stagnating. The client wanted to raise the budget. But our analysis showed the bottleneck was in the funnel, not in the money.
Our strategy: three steps with big impact
1. Funnel analysis with real user data
We analyzed the whole path from the first click to the conversion. Heatmaps and session recordings showed exactly where visitors dropped off. Those insights fed straight into new landing pages.
2. Better budget allocation
According to the project account, the existing budget was reallocated: 70 percent to performance and 30 percent to branding. That describes this case, not a recommended split for every account.
3. Smarter retargeting
The project account describes creatives adapted to funnel stages, from awareness to trust. The available figures do not establish the isolated effect of that change on conversion rate.
The results
- Leads: up 50 percent
- Conversion rate: from 2.4 to 3.8 percent
- ROAS: up 42 percent
The reported results describe the project’s development. They do not establish the separate contribution of funnel analysis, budget allocation or retargeting.
What you can take from this
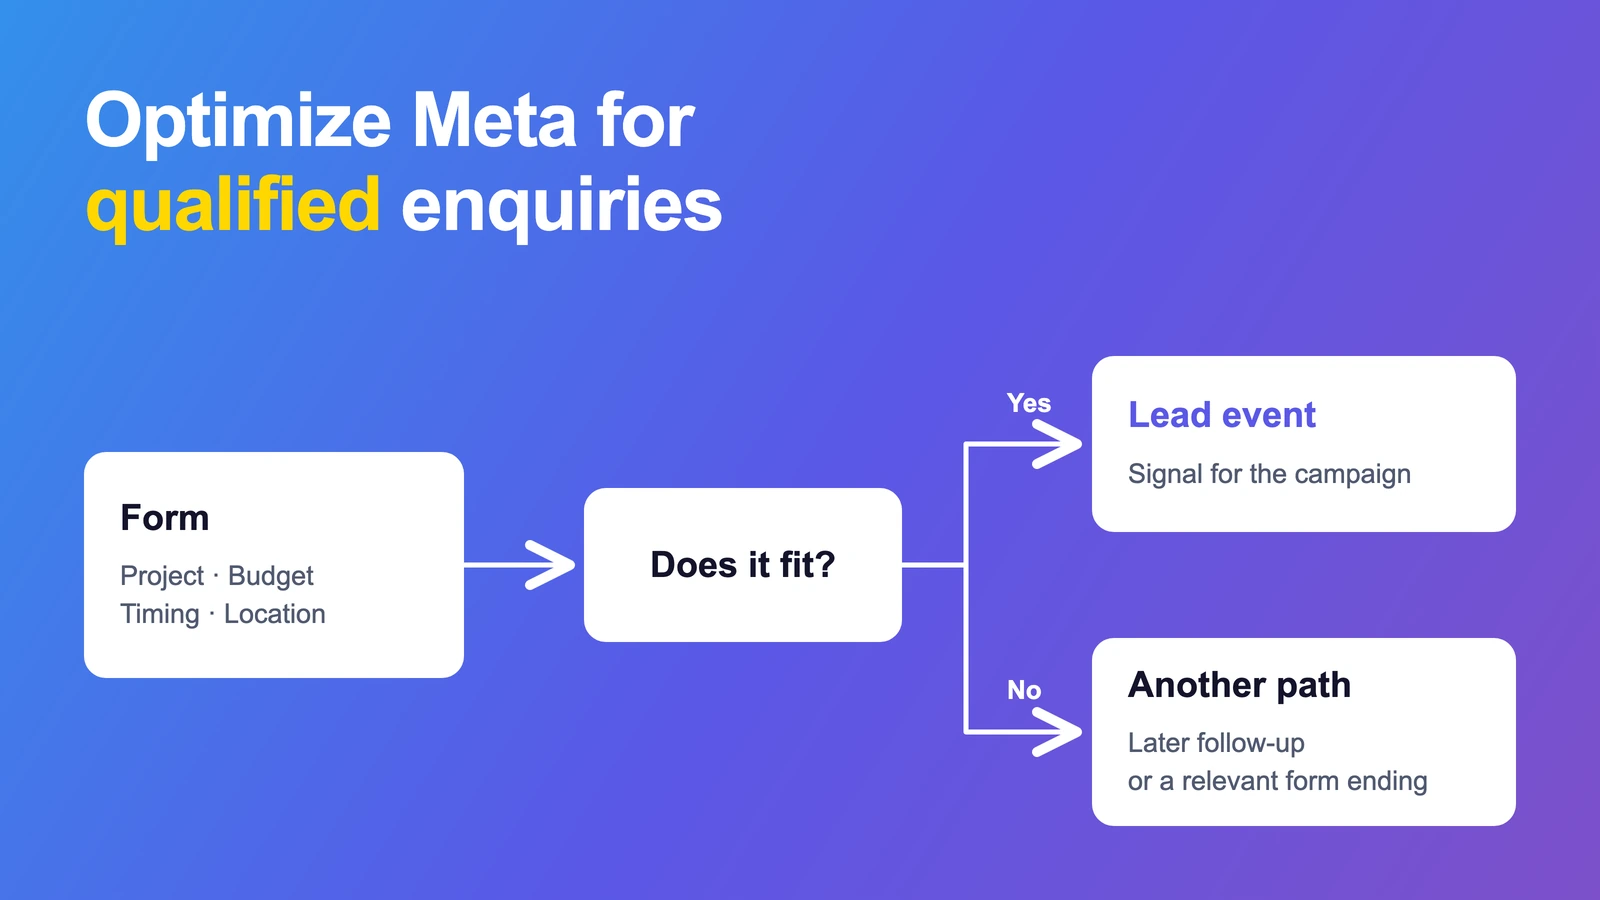
Check where visitors leave, which leads reach sales and which message fits the next step. Use your own data to measure whether a change brings more customers.
Case data basis
The percentages come from the existing published account of this client project. The period, budget basis, lead definition and underlying records are not disclosed here. These figures are not a benchmark and do not isolate the effect of any individual change.